Explore All Exams at KGS

All Exams
Explore All Exams at KGS
Khan Sir Courses
Geography I Polity I History | World Map I Indian Map I Economics I Biology
UPSC & State PSC
UPSC I BPSC I UP-PSC I MP-PSC

State Exams
UP I Bihar I MP | Rajasthan
NEET | JEE | CUET
NEET | JEE | CUET
Defence Exams
NDA I CDS I CAPF I AFCAT I SSB I Agniveer
Police Exams
UP SI | Bihar SI | Delhi Police | UP Constable

SSC Exams
CGL I CPO I CHSL I MTS I SSC GD I Delhi Police
Foundation Courses
Physics I Chemistry I Biology I History I Geography I Polity I NCERT I Math I English | Map I Reasoning
Railway Exams
RRB | RPF
Teaching Exams
TET | Teaching | UGC

Banking Exams
SBI | RBI | IBPS
Engineering Exams
Civil | Electrical | Mechanical
UGC NET
UGC NET/JRF
Current Affairs provides you with the best compilation of the Daily Current Affairs taking place across the globe: National, International, Sports, Science and Technology, Banking, Economy, Agreement, Appointments, Ranks, and Report and General Studies
Current Affairs
SYLLABUS
GS-3: Indian Economy and issues relating to planning, mobilization of resources, growth, development and employment.
Context: As Make in India completes 12 years on 25 September 2026, India’s manufacturing landscape has expanded across key industries, components, machinery, strategic materials and advanced technologies.
About Make in India
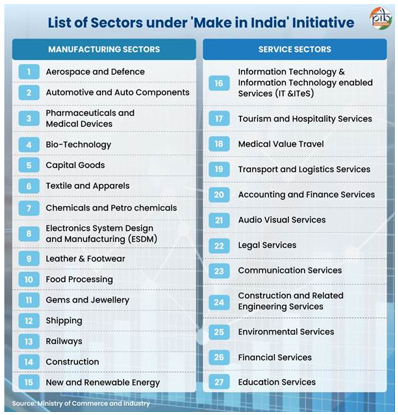
Achievements of Make in India
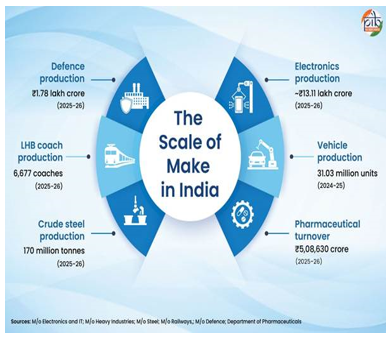
Need and Significance
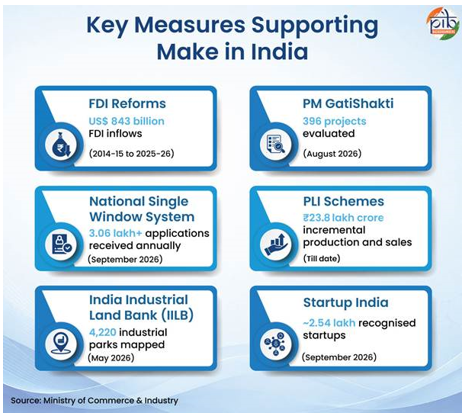
Gaps / Challenges
Khan Global Studies App
With our training programs, learning online can be a very exciting experience. Take the next step toward achieving your professional and personal objectives.
Course Related Query:
Ask Your DoubtsStore Related Query:[email protected]NEET | JEE | CUET
NCERT Books
Resources
We love learning. Through our innovative solutions, we encourage ourselves, our teams, and our Students to grow. We welcome and look for diverse perspectives and opinions because they enhance our decisions. We strive to understand the big picture and how we contribute to the company’s objectives. We approach challenges with optimism and harness the power of teamwork to accomplish our goals. These aren’t just pretty words to post on the office wall. This is who we are. It’s how we work. And it’s how we approach every interaction with each other and our Students.
Come with an open mind, hungry to learn, and you’ll experience unmatched personal and professional growth, a world of different backgrounds and perspectives, and the freedom to be you—every day. We strive to build and sustain diverse teams and foster a culture of belonging. Creating an inclusive environment where every students feels welcome, appreciated, and heard gives us something to feel (really) good about.